- 29/10/2026
- Umesh Bagad
- 0 Comments
- Home Loan
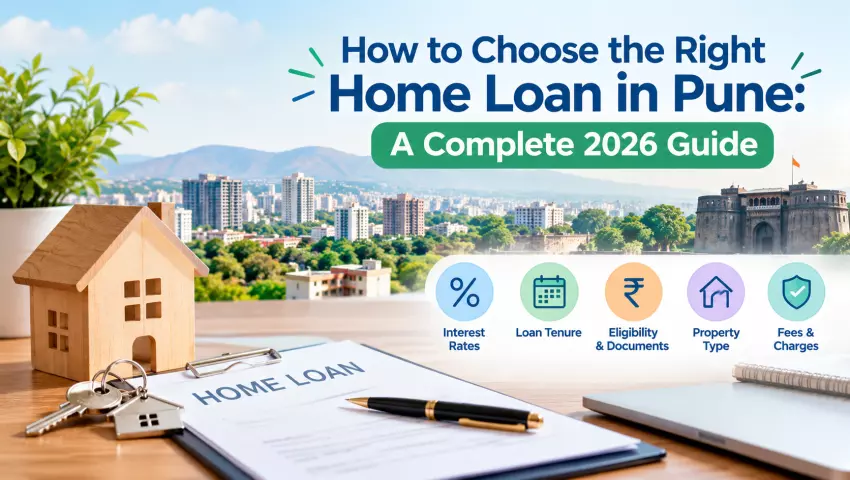
How to Choose the Right Home Loan in Pune? A Complete 2026 Guide
Buying a home is a major financial decision, and choosing the wrong loan can put unnecessary pressure on your monthly budget. With different banks and financial institutions offering different interest rates, repayment periods, and charges, comparing home loan options can feel complicated.
Understanding how to choose the right home loan in pune starts with more than finding the lowest interest rate. You need to consider your income, down payment, monthly EMI, total interest, property documents, and the conditions offered by the lender.
This guide explains the important factors Pune homebuyers should evaluate before applying for a home loan, helping you compare options and make a more informed financial decision.
Home Loan Comparison: What Should You Check First?
1. Calculate Your Home Buying Budget:
Consider the complete purchase cost:
The cost of buying a home may include more than the property's advertised price. Depending on the transaction, you may also need to budget for stamp duty, registration, applicable taxes, legal assistance, moving expenses, and initial repairs or furnishings. For example, someone purchasing an apartment in Wakad, Baner, Hinjawadi, Ravet or Pimpri-Chinchwad should prepare a complete budget based on the specific property and transaction.
Plan your down payment:
A down payment reduces the amount you need to borrow. A smaller loan may mean a lower EMI and less total interest, depending on the interest rate and tenure. However, avoid using all your savings for the down payment. Keep an emergency reserve for unexpected expenses, changes in income and family responsibilities.
Set a comfortable EMI limit:
Your maximum eligible loan amount may be different from the amount you can comfortably repay. Calculate your take-home income after considering existing EMIs, household expenses, insurance, savings and other regular commitments. A sensible home buying budget should leave enough room for everyday expenses and unexpected financial changes.
2. Understand Home Loan Eligibility:
Income and employment profile:
Salaried applicants may be assessed using salary slips, employment records and bank statements. Self-employed applicants may need to provide income tax returns, financial statements and business bank records. Lenders may consider income stability, existing obligations and the consistency of earnings.
Credit history and existing loans:
Your credit history helps a lender assess your previous repayment behaviour. Existing personal loans, vehicle loans and other financial commitments may also affect your borrowing capacity. Check your credit report for errors before applying. A particular credit score does not guarantee approval because lenders consider several factors.
Joint home loan applications:
Eligible family members may be able to apply jointly, subject to lender rules. The lender may consider the co-applicant's income and financial obligations. Before applying jointly, understand the repayment responsibilities and ownership arrangements involved.
3. Compare Fixed and Floating Home Loan Interest Rates:
Interest rates are important, but understanding how they can change is equally important.
Fixed interest rates:
A fixed-rate arrangement keeps the rate unchanged for the period specified in the loan agreement. Some products may have different conditions after the fixed period. Check the applicable fixed period, conversion conditions and other contractual terms before choosing this option.
Floating interest rates:
A floating interest rate may change with the relevant benchmark and the lender’s terms. Changes can affect the EMI, repayment tenure or both. Ask the lender which benchmark applies, how frequently the rate resets and how changes will be communicated.
Which option is suitable?
A fixed-rate arrangement may suit borrowers who value predictability for the agreed period. A floating-rate arrangement may suit borrowers who are comfortable with possible changes in repayment obligations. Neither option is automatically cheaper. Compare the actual offers and evaluate whether you could manage an increase in repayments.
Read More – Fixed vs. Floating Interest Rates
4. Calculate Your Home Loan EMI and Total Interest:
Your Equated Monthly Instalment (EMI) is the amount you repay every month according to the loan’s repayment schedule. It depends mainly on the principal amount, applicable interest rate and tenure.
Example: EMI comparison for a ₹40 lakh home loan
The following illustration assumes a ₹40 lakh loan at a constant annual interest rate of 8.5%, calculated using a standard monthly reducing-balance EMI formula.
Choose a manageable repayment period:
A shorter tenure generally requires higher EMIs but reduces total interest under the same-rate assumptions. A longer tenure can make repayments more manageable but may increase the overall borrowing cost. Use an EMI calculator to compare scenarios before choosing.
5. Compare Total Loan Costs, Not Just Interest Rates:
Two lenders may advertise similar rates but have different fees and loan conditions.
Check processing and verification charges:
Depending on the lender and transaction, charges may include processing fees, legal verification, technical valuation and other applicable costs. Ask for a written breakdown before accepting an offer.
Review the Key Facts Statement:
Where applicable, review the lender’s Key Facts Statement (KFS), including the Annual Percentage Rate (APR), repayment schedule and disclosed charges. The APR helps borrowers understand the annualised cost of credit under the applicable disclosure framework.
Official reference: RBI Loan Disclosure Guidance.
Understand prepayment conditions:
Ask about partial prepayments, early loan closure and any applicable conversion conditions. The rules and charges can vary according to the loan category, borrower and applicable regulations. Check the terms relevant to your specific loan instead of assuming that all products have the same conditions.
6. Verify Property Documents Before Applying:
A home loan application involves both borrower assessment and property verification.
Check ownership and legal documents:
Depending on the transaction, documents may include the agreement for sale, title records, ownership documents, approved plans and other applicable permissions. Resale properties may require additional checks relating to previous ownership and outstanding obligations. Consider independent legal advice where appropriate.
Verify project details through MahaRERA:
For projects where registration applies, review the relevant details through the Maharashtra Real Estate Regulatory Authority. Official resource: MahaRERA Project Search. Review the available project information and disclosures. Registration does not replace all other legal and property checks.
Understand lender verification:
The lender may conduct legal and technical assessments before sanctioning or disbursing the loan. Property documents, valuation and applicable approvals can influence the lending decision. Do not assume that a property is fully approved for financing until the lender has completed its assessment.
7. Compare Banks and Home Loan Lenders:
Different lenders have different eligibility policies, interest rates, documentation requirements and service processes.
Compare written offers:
Where possible, compare offers using the same loan amount and tenure. Review the interest rate, EMI, APR, fees, repayment flexibility and other conditions.
Check processing requirements:
Ask which documents are required, what verification stages apply and what conditions must be fulfilled before disbursement. An advertised processing time does not guarantee approval. Choose a lender that explains the terms clearly and provides the necessary documentation.
8.How to Choose the Right Home Loan in Pune
Comparing lenders and preparing financial and property documents can be challenging, especially for first-time homebuyers. A Home Loan Consultant in Pune may help you understand suitable options, organise documents and coordinate the application process.
Questions to ask before choosing a consultant:
- Which lenders can you help me compare?
- How will you assess my requirements and repayment capacity?
- Which documents will I need?
- Are there any consultancy charges?
- How will I receive application updates?
- Can you explain the total cost of each suitable offer?
A consultant should explain available options transparently. No consultant can guarantee that a lender will approve an application.
How Pinakin Global Fintech can help?
Pinakin Global Fintech Pvt. Ltd. assists customers in exploring home loan options through 32+banks and NBFCs, subject to lender availability and eligibility requirements. Its home loan service can be explored here: Home Loan Consultant in Pune. Contact the team to discuss your requirements and understand the available financing options.
9. Understand the Home Loan Application Process:
Although the exact process varies by lender, the following stages provide a useful overview.
- Step: Assess your finances: Review your income, existing loans, credit history, savings and expected property expenses. Estimate a comfortable EMI before deciding on the loan amount.
- Step: Compare lenders and prepare documents: Review suitable offers and prepare the financial and property documents requested by the lender. Submit accurate information and clarify any requirements you do not understand.
- Step: Complete verification and review the sanction terms: The lender may verify your credit profile, income, property valuation and legal documents. If the loan is approved, review the sanction terms, interest rate, fees, repayment schedule and other conditions before completing the required formalities. Disbursement remains subject to the lender’s conditions.
10. Should Existing Borrowers Consider a Balance Transfer or Top-Up?
Existing borrowers can review their loan terms when their financial circumstances or available offers change.
Home loan balance transfer:
A balance transfer moves an outstanding home loan to another lender, subject to approval. Compare potential interest savings against fees, remaining tenure and other conditions before deciding. Learn more about home loan balance transfer options.
Home loan top-up:
Eligible borrowers may be able to obtain additional financing linked to an existing home loan. Availability and terms depend on the lender’s policies and the borrower’s eligibility. Before accepting additional borrowing, consider the revised EMI, total repayment obligation and intended use of the funds.
Conclusion: Choose a Home Loan That Fits Your Financial Goals
Understanding how to choose the right home loan in pune means looking beyond the advertised interest rate. Your income, down payment, EMI, repayment tenure, property documents and lender conditions all influence the final decision.
For homebuyers in Pune and Pimpri-Chinchwad, comparing suitable financing options and reviewing the total borrowing cost can help make the process easier to understand.
Pinakin Global Fintech Pvt. Ltd. assists customers in exploring home loan options through banks and NBFCs. Contact the team to discuss your requirements and learn more about the available services.
Pinakin Global Fintech Pvt. Ltd.
Phone: +91 7066453322 / 9890033002
Frequently Asked Questions:
To choose the right home loan in Pune, compare interest rates, EMI, processing fees, eligibility, and repayment flexibility. Pinakin Global Fintech Pvt. Ltd., a trusted home loan consultant in Pune, can help you explore suitable home loan options and make an informed financing decision.
Pinakin Global Fintech provides home loan consultancy assistance, including guidance on financing options, documentation and application coordination with lenders.
The 20-30-40 rule is a budgeting guideline that may suggest a 20% down payment, housing costs around 30% of income, and a manageable overall budget. Pinakin Global Fintech can help you understand home loan affordability and plan your home financing.
Choose a lender based on interest rates, processing fees, eligibility, repayment flexibility, and service quality. Pinakin Global Fintech, a Home Loan Agent in Pune, can help you compare available home loan options.
You can shorten your loan tenure by increasing your EMI or making regular principal prepayments, subject to your loan terms. Pinakin Global Fintech can help you understand home loan repayment options and plan your finances more effectively.