- +91 7066453322 Call Us Now
- info@pinakinfintech.com Drop Us a Line
Loan Against Property in Pune
Unlock the Value of Your Property with a Loan Against Property
Need substantial funds for your business, a medical emergency or a major expense—without selling your property? A Loan Against Property in Pune lets you pledge an eligible residential or commercial property to a bank or NBFC and raise funds based on its value, your income and your repayment capacity. You keep ownership and, in most cases, continue to use the property.
At PINAKIN GLOBAL Fintech Pvt. Ltd., we work as a trusted loan against property consultant in Pune with 25+ years of financial-industry experience. We compare LAP loan in Pune options across 32+ banks and NBFCs and support you from eligibility check to disbursement—whether you live in Pune city, PCMC or Pimpri-Chinchwad
25+
Years of Industry Experience
32+
Banks & NBFC Partners
5,000+
Happy Customers
₹10,000+ Cr
Loan Assistance
What is a Loan Against Property (LAP)?
A secured loan against property is financing in which the lender holds a charge on your property until the loan is fully repaid. Because the lender has security, LAP can offer higher loan amounts, longer tenures and often lower interest rates than many unsecured loans.
The final amount, rate and tenure depend on the property value, your income, credit profile and the lender’s policy. Funds can generally be used for eligible personal, professional and business needs, subject to lender terms.
Why Consider a Loan Against Property?
If you own a property and require a substantial amount of funding, selling the property may not always be the preferred option.
Pune’s mix of SMEs, manufacturers, IT professionals, traders and independent practitioners creates steady demand for large-ticket funding. Common reasons to take a property loan in Pune include:
- Business expansion
- Working capital requirements
- Professional practice expansion
- Higher education expenses
- Medical and emergency expenses
- Debt consolidation
- Home renovation
- Major personal financial requirements
- Investment-related financial requirements
- Other eligible personal or business needs
If your requirement is specifically related to purchasing, constructing or financing a home, explore our Home Loan in Pune solutions.
The final permitted use of funds depends on the selected lender and loan terms.
Key Features and Benefits of Loan Against Property
- Higher Funding Potential
Since the loan is secured against property, lenders may provide a higher loan amount compared with certain unsecured loan products. The actual amount depends on property valuation, loan-to-value norms, income and repayment capacity. - Competitive Interest Rates
A secured loan may offer more competitive interest rates than some unsecured borrowing options. The applicable rate depends on the lender, applicant profile, credit history and other eligibility factors. - Flexible Repayment Tenure
Depending on the lender and applicant profile, LAP may be available with a longer repayment tenure. A suitable tenure can help manage monthly EMI obligations. - Continue to Own Your Property
The borrower generally continues to own and use the property while it is pledged as security for the loan, provided the terms of the loan are followed. - Multiple Financial Uses
Loan Against Property can be used for several eligible personal, professional and business financial requirements, subject to the lender’s policies. - Access to Multiple Lenders
Instead of approaching lenders individually, PINAKIN GLOBAL Fintech helps you explore options across its network of banks and NBFCs. - Professional Documentation Support
Our team helps you understand the documentation requirements and coordinates the application process to reduce unnecessary delays.
Eligible Properties for Loan Against Property
A Loan Against Property can generally be obtained by pledging an eligible residential property, subject to lender policies, property valuation and legal verification.
Depending on the lender, eligible properties may include:
- Residential Flats and Apartments
- Independent Houses
- Bungalows
- Self-Occupied Residential Properties
- Rented Residential Properties
- Other eligible residential properties accepted by the lender
Property eligibility can vary depending on ownership, title documents, location, construction status, market value, legal clearance and the lender’s internal policies.
Note: Commercial and industrial financing requirements are evaluated separately based on the relevant loan product and lender criteria. If you require financing specifically for commercial requirements, explore our Commercial Loan solutions.
Loan Against Property Eligibility
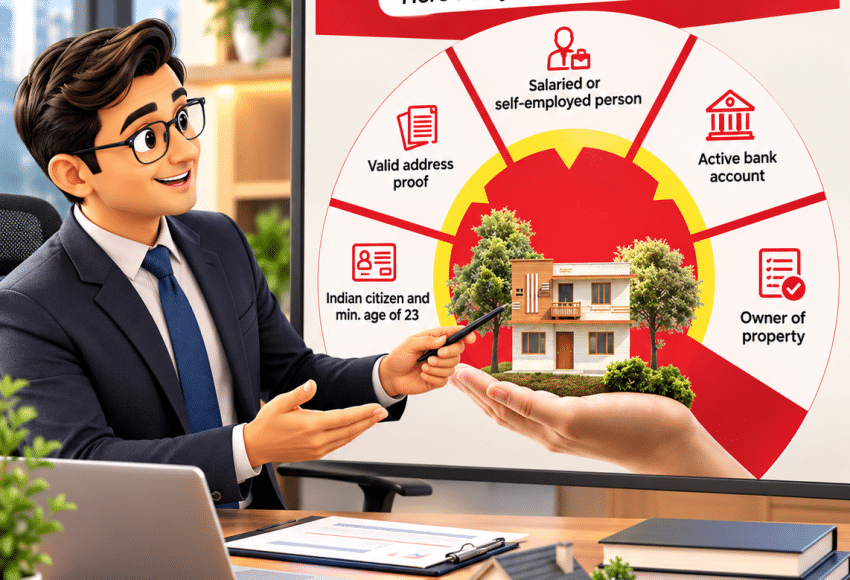
Every lender has its own eligibility criteria. However, the following factors are commonly evaluated:
Property Value
The market value and eligible loan-to-value ratio of the property influence the potential loan amount.
Income and Repayment Capacity
Your income and existing financial obligations help the lender assess whether you can comfortably repay the proposed loan.
Credit Profile
Credit history and repayment behaviour may influence loan approval and the interest rate offered.
Property Documents
Clear ownership and legally acceptable property documentation are important for property verification.
Applicant Profile
Age, employment or business profile, income stability and existing obligations may also be considered.
Location and Property Status
The property’s location, construction status and legal approvals may affect its eligibility.
Who Can Apply for a Loan Against Property in Pune ?
Loan Against Property may be suitable for applicants with an eligible property and a stable source of income.
Depending on lender policies, eligible applicants may include:
- Salaried Professionals
- Self-Employed Professionals
- Business Owners
- Entrepreneurs
- Proprietors
- Partnership Firm Partners
- LLP Applicants
- Private Limited Company Applicants
- Other eligible borrowers
Eligibility is not determined by property ownership alone. Lenders generally consider income, credit history, existing liabilities, repayment capacity, property value and legal documentation.
Documents Required for Loan Against Property
1. KYC Documents:
- Aadhaar Card
- PAN Card
- Passport or Driving Licence
- Address Proof
2. Income Documents:
For Salaried Applicants:
- Salary Slips
- Bank Statements
- Form 16
- Income Tax Returns (if applicable)
For Self-Employed & Businesses:
- Income Tax Returns
- Audited Financial Statements
- Bank Statements
- GST Returns
- Balance Sheet & Profit & Loss Statement
3. Property Documents:
- Title Deed
- Sale Deed
- Property Tax Receipts
- Approved Building Plan
- Occupancy Certificate (if applicable)
- Previous Chain of Property Documents
- Encumbrance Certificate (if required)
Our documentation specialists ensure that your application is complete, accurate, and processed efficiently.
How Much Loan Can You Get Against Your Property?
The loan amount is not determined by property value alone.
Lenders may consider:
- Property market value
- Applicable loan-to-value ratio
- Applicant income
- Existing EMIs and liabilities
- Credit profile
- Repayment capacity
- Property type and location
- Legal and technical verification
- Lender-specific policies
For this reason, two applicants with properties of similar value may receive different loan offers.
PINAKIN GLOBAL Fintech can help you compare available lending options based on your financial profile and property details.
Loan Against Property Interest Rate
The interest rate for a Loan Against Property varies from one lender to another.
It may depend on:
- Applicant’s credit profile
- Income and financial stability
- Loan amount
- Loan tenure
- Property value
- Property location
- Existing liabilities
- Type of applicant
- Lender’s internal credit policy
Rather than selecting a lender only on the advertised interest rate, it is important to compare the overall cost of borrowing, including applicable processing fees and other charges.
PINAKIN GLOBAL Fintech helps borrowers understand and compare available loan options before proceeding.
Loan Against Property for Business Owners
Business owners may consider LAP when they require substantial funding for eligible business requirements.
Depending on lender policies, funds may be used for purposes such as:
- Business expansion
- Working capital
- Business-related expenses
- Professional practice expansion
- Equipment or operational requirements
- Debt restructuring or consolidation, where permitted
The availability and permitted end use of funds depend on the lender’s policy and applicant profile.
For dedicated business financing requirements, PINAKIN GLOBAL Fintech can also help you explore suitable business loan solutions.
Loan Against Property for Salaried Professionals
Salaried individuals who own eligible residential property may consider LAP for substantial financial requirements.
Lenders may assess:
- Monthly income
- Employment stability
- Credit history
- Existing loan obligations
- Property value
- Repayment capacity
Our advisors can help salaried applicants understand the available options and documentation requirements before approaching suitable lenders.
Loan Against Property for Self-Employed Professionals
Self-employed professionals and entrepreneurs may require significant funds for personal or professional financial needs.
Lenders may evaluate:
- Business or professional income
- ITRs
- Banking transactions
- Existing liabilities
- Credit history
- Property value
- Business continuity
PINAKIN GLOBAL Fintech helps self-employed applicants identify suitable lender options based on their financial profile.
Common Mistakes to Avoid When Taking a Loan Against Property
Before applying for LAP, borrowers should carefully evaluate the following:
1. Borrowing More Than You Need
A higher eligible loan amount does not mean you need to borrow the entire amount. Borrow according to your actual financial requirement and repayment capacity.
2. Comparing Only Interest Rates
The lowest advertised interest rate may not always mean the lowest overall borrowing cost. Check processing fees, other charges, tenure and repayment terms.
3. Ignoring Existing Liabilities
Existing EMIs and financial obligations can affect your eligibility and monthly repayment capacity.
4. Incomplete Property Documentation
Missing or unclear property documents can delay legal verification and loan processing.
5. Choosing a Lender Without Comparison
Different lenders may offer different rates, loan amounts, tenure and eligibility criteria. Comparing suitable options can help you make a better decision.
6. Not Understanding the Loan Terms
Before accepting an offer, understand the interest rate, tenure, EMI, fees, prepayment conditions and other applicable terms.
PINAKIN GLOBAL Fintech can help you understand these factors before you proceed with your application.
Loan Against Property Process
Applying for a Loan Against Property in Pune becomes easier when your eligibility and documents are prepared correctly.
Step 1: Share Your Requirement
Tell us about your funding requirement, applicant profile and property details.
Step 2: Initial Eligibility Assessment
Our team reviews your basic financial information, income and existing obligations to understand potential eligibility
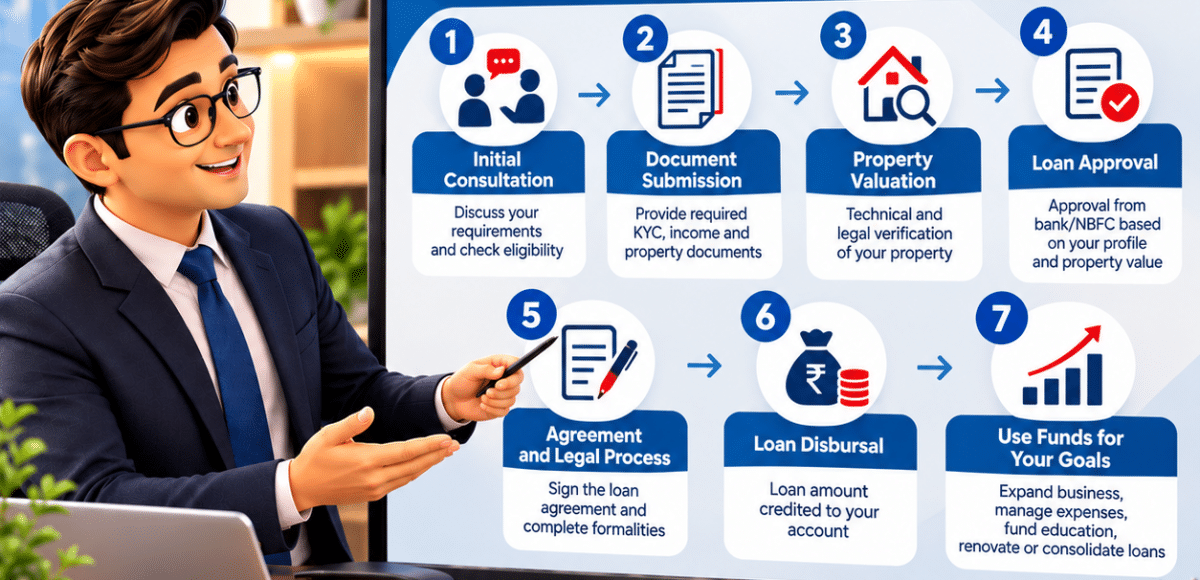
Step 3: Property Assessment
The property details and documents are reviewed for preliminary eligibility. The selected lender may conduct legal and technical verification.
Step 4: Compare Lender Options
We help you explore suitable options from our network of banks, NBFCs and financial institutions.
Step 5: Documentation
You submit the required KYC, income and property documents based on the lender’s requirements.
Step 6: Legal and Technical Verification
The lender conducts the required property valuation, legal checks and other verification processes.
Step 7: Loan Sanction
After successful assessment, the lender issues the sanction based on the approved terms.
Step 8: Disbursement
After completion of the required formalities and documentation, the approved loan amount is disbursed according to the lender’s terms.
Loan Against Property vs Personal Loan
Both LAP and personal loans can provide access to funds, but they work differently.
Feature | Loan Against Property | Personal Loan |
Security | Property is pledged | Generally unsecured |
Potential Loan Amount | Generally higher | Usually lower |
Interest Cost | May be more competitive | Generally higher |
Tenure | Can be longer | Usually shorter |
Documentation | Property documentation required | Usually simpler |
Processing | Includes property verification | Generally faster |
If you do not wish to pledge property as security, you may also consider a Personal Loan for eligible personal financial requirements, subject to lender eligibility and terms.
The right option depends on your financial requirement, eligibility, repayment capacity and borrowing profile.
Why Choose PINAKIN GLOBAL Fintech Pvt. Ltd.?
Choosing the right lender for a Loan Against Property can significantly impact your borrowing cost and repayment flexibility. At PINAKIN GLOBAL Fintech Pvt. Ltd., we compare multiple lenders, negotiate competitive terms, and provide unbiased financial guidance to help you make the right decision.
Our client first approach ensures complete transparency, faster processing, and personalised support throughout the loan journey.
Why customers trust us?
- 25+ Years of Financial Industry Experience
- 32+ Banking & NBFC Partners
- High-Value Loan Assistance
- Competitive Interest Rate Comparison
- Quick Eligibility Assessment
- Faster Loan Processing
- End-to-End Documentation Support
- Dedicated Relationship Managers
- Transparent & Ethical Financial Advisory
Our mission is to help you maximise the financial value of your property while ensuring a smooth borrowing experience.
What Our Customers Are Saying
Frequently Asked Questions:
A Loan Against Property is a secured loan where an eligible property is pledged as collateral to obtain financing from a bank, NBFC or financial institution.
Common documents include KYC documents, income proof, bank statements and property ownership documents. Exact requirements vary by lender.
Since LAP is secured against property, it may offer more competitive interest rates than some unsecured loans. However, the actual rate depends on the applicant and lender.
A Loan Against Property can be used for business expansion, education, medical expenses, working capital, debt consolidation, home renovation, and various other personal or business purposes.
Approval timelines depend on documentation, property verification, and lender procedures. Our experts work closely with lenders to ensure the fastest possible processing.
Unlock the True Value of Your Property
Your property can help you achieve bigger financial goals without giving up ownership. Whether you need funds for business growth, professional expansion, education, or personal requirements, a Loan Against Property provides a secure, affordable, and flexible financing solution.
At PINAKIN GLOBAL Fintech Pvt. Ltd., we combine expert financial advice, strong banking partnerships, and end-to-end support to help you secure the best Loan Against Property solution tailored to your needs.
Contact our loan experts today and turn your property into a powerful financial asset for your future growth.
Want a Detailed Loan Eligibility Report?
Know your bank-wise home loan eligibility and estimated loan amount from multiple lenders. Fill out the form.
Enquire / Apply for Loan!
WhatsApp us