- 30/10/2026
- Umesh Bagad
- 0 Comments
- Home Loan
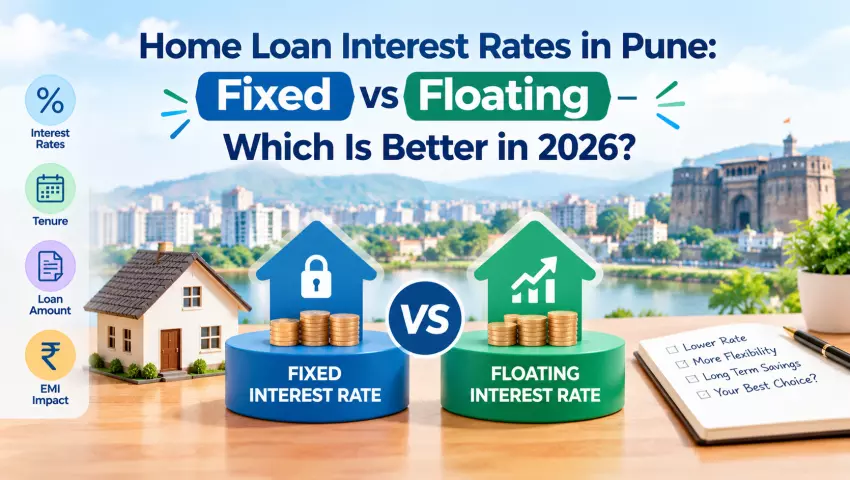
Home Loan Interest Rates in Pune: Fixed vs Floating Which Is Better in 2026?
Choosing between fixed and floating interest rates is an important decision when applying for a home loan. Your interest rate affects your monthly EMI, repayment planning and the total cost of borrowing. For buyers comparing home loan interest rates in Pune, understanding both options can help avoid unexpected financial pressure.
A fixed rate offers greater predictability during the agreed period, while a floating rate can change according to its applicable benchmark and loan terms. Neither option is automatically cheaper for every borrower.
This guide explains how both rates work, how RBI policy can influence floating rates, and what to consider before choosing a home loan with Pinakin Global Fintech Pvt. Ltd.
Fixed vs Floating Home Loan Interest Rates: Quick Comparison
Important: Some fixed-rate products have a fixed period rather than a rate fixed for the entire tenure. Always check the loan agreement.
1. What Is a Fixed Home Loan Interest Rate?
A fixed home loan interest rate remains unchanged for the period specified in the loan agreement. This can make monthly budgeting easier because your interest rate does not automatically move with market changes during that period.
Benefits of a fixed interest rate:
- Predictable repayments: You can plan your monthly budget with greater confidence during the fixed period.
- Protection from rate increases: Market rate increases generally do not affect your agreed fixed rate during that period.
- Easier financial planning: Predictable repayments can help borrowers manage household expenses and savings.
Limitations of a fixed interest rate:
If market interest rates decrease, your agreed rate may not decrease automatically. You might continue paying the same rate while some floating-rate borrowers receive a lower rate. Also, not every product is fixed for the entire loan tenure. Check whether a reset clause, conversion option or other condition applies after a specified period.
Who should consider a fixed rate?
A fixed rate may suit borrowers who prioritise repayment stability and have limited room in their monthly budget for unexpected increases. Compare the actual fixed-rate offer with available floating-rate options before deciding.
2. What Is a Floating Home Loan Interest Rate?
A floating home loan interest rate can change during the loan tenure according to its benchmark and the conditions specified in the agreement.
How does a floating rate work?
A floating rate may be linked to a benchmark, such as an external benchmark used by the lender, plus an applicable spread. Your loan agreement should explain the benchmark, spread and rate-reset conditions.
When the applicable benchmark changes, your lending rate may change according to the lender’s terms. This can affect your EMI, repayment tenure or both.
Benefits of a floating rate:
If the applicable benchmark decreases and the change is passed on under your loan terms, your interest rate may fall. Depending on how your lender adjusts repayments, you may pay a lower EMI, repay the loan sooner or reduce the total interest cost.
However, these savings are not guaranteed. Future benchmark movements are uncertain.
Risks of a floating rate:
If the applicable benchmark increases, your borrowing cost may rise. Your lender may increase the EMI, extend the tenure or adjust both, depending on the agreement and applicable rules.
Before choosing a floating rate, consider whether you could manage a higher EMI without compromising essential expenses or emergency savings.
3. How Does RBI Influence Home Loan Interest Rates?
The Reserve Bank of India (RBI) influences borrowing conditions through monetary policy, including its policy repo rate. However, RBI does not directly set every bank’s home loan interest rate. Lenders determine their applicable rates under the relevant regulatory framework, benchmark arrangements and loan terms.
What is the repo rate?
The repo rate is the rate at which RBI lends short-term funds to eligible banks against securities under the applicable facility. Changes in the repo rate can influence banks’ funding conditions and lending benchmarks, but the effect on an individual home loan depends on its rate structure and reset terms.
How can a repo rate change affect your EMI?
For a floating-rate home loan linked to an external benchmark, a benchmark change can affect the applicable interest rate when the loan resets.
- If the relevant benchmark decreases: Your floating interest rate may decrease, potentially reducing your EMI or overall interest cost.
- If the relevant benchmark increases: Your floating interest rate may increase, potentially raising your EMI or extending your repayment tenure.
- If your loan has a fixed rate: A market rate change generally does not alter the agreed rate during the fixed period, subject to your contract.
The impact may not happen immediately because reset dates and lender terms matter.
4. Fixed vs Floating Home Loan EMI: A Practical Example
Let’s compare how a fixed rate and a floating rate could affect a ₹40 lakh home loan.
Assume the loan starts at an annual interest rate of 8.5% with a 20-year tenure. For the floating-rate examples, the rate changes after the first 12 monthly payments, and the EMI is recalculated for the remaining 19 years.
A Practical Example calculations only. The first 12 EMIs are calculated at 8.5%. The floating-rate examples assume the rate changes after one year and the EMI is recalculated for the remaining 19 years. Figures are rounded and exclude fees. Actual lender calculations may differ.
What does this comparison mean?
- When the floating rate decreases: In this example, the revised EMI falls by about ₹2,406 per month compared with the unchanged-rate scenario. Total interest could be approximately ₹5.48 lakh lower.
- When the floating rate increases: The revised EMI rises by about ₹2,485 per month. Total interest could be approximately ₹5.67 lakh higher than in the unchanged-rate scenario.
- When the rate stays unchanged: The illustrative EMI and total interest remain the same as the 8.5% scenario.
These figures are scenarios, not predictions of future interest rates. A lender may change the EMI, tenure or both when a floating rate resets. Ask for a revised repayment schedule before making a financial decision.
5. Which Home Loan Interest Rate Is Better in Pune?
Consider your repayment capacity:
If your monthly budget is tight, predictable repayments may be particularly valuable. If you have sufficient financial flexibility to manage changing EMIs or a longer repayment period, you may be more comfortable with a floating rate. Keep emergency savings and avoid choosing the maximum loan amount simply because the lender offers it.
Compare written lender offers:
When comparing home loan interest rates in Pune, use the same loan amount and tenure wherever possible. Review:
- Applicable interest rate and EMI
- Fixed period or floating-rate benchmark
- Spread and reset frequency
- Processing fees and other disclosed charges
- Prepayment conditions and conversion charges
- Key Facts Statement (KFS) and Annual Percentage Rate (APR), where applicable
A lower advertised rate does not automatically mean a lower overall borrowing cost. Review the full loan terms before accepting an offer.
6. Can You Switch From Floating to Fixed Interest Rates?
Switching may be possible if your lender offers the option and you meet its eligibility requirements. It is not safe to assume that every home loan can be converted automatically or without charges.
Ask your lender whether a fixed-rate product is available, whether you qualify, what conversion charges apply and how the change would affect your EMI and remaining tenure.
Request the revised terms in writing before agreeing. You should also confirm which RBI provisions apply to your particular home loan and borrower category.
How Pinakin Global Fintech Can Help?
Comparing lenders can involve understanding interest rates, eligibility, documentation, repayment terms and additional charges.
Pinakin Global Fintech Pvt. Ltd. helps customers explore home loan options through its network of banks and NBFCs, subject to lender availability and eligibility requirements. You can learn more about its services here: Home Loan in Pune — Pinakin Global Fintech.
Before proceeding, compare written offers and confirm the final rate, charges and approval conditions directly with the relevant lender. Loan approval is not guaranteed.
Frequently Asked Questions:
A fixed rate may suit borrowers who value predictable repayments during the agreed period. A floating rate may suit borrowers who can manage interest-rate changes. Compare actual offers before deciding.
Yes, they can influence floating-rate loans through applicable benchmarks. The effect and timing depend on your loan’s benchmark, reset schedule and lender terms.
Yes. If the applicable benchmark or contractual pricing changes, your interest rate may increase, raising the EMI, extending the tenure or affecting both.
It may be possible depending on the lender’s products, policies and your loan terms. Check eligibility and conversion charges before switching.
Compare written offers for the same loan amount and tenure. Review the interest rate, EMI, disclosed fees, benchmark, reset conditions and repayment flexibility.